Buying Your First Home Doesn’t Have to Be Overwhelming
Buying your first home is one of the biggest financial decisions you’ll ever make—but it doesn’t have to feel confusing or stressful.
As a first-time home buyer, you may qualify for special programs, lower down payment options, and government incentives designed to make homeownership more accessible. With the right mortgage strategy, you can buy confidently while staying within your budget—both now and long-term.
Lower Down Payment Options
Buy with as little as 5% down, depending on the purchase price.
Access First-Time Buyer Incentives
Take advantage of rebates, land transfer tax credits, and government programs.
Clear Guidance From Start to Finish
From pre-approval to closing day, we guide you every step of the way.
How Buying Your First Home Works
The first step is understanding what you can afford. Getting pre-approved helps you set a realistic budget, lock in a rate, and shop with confidence—before making an offer.
Example:
Purchase Price: $650,000
Down Payment (5%): $32,500
Mortgage Amount: $617,500
A proper pre-approval ensures there are no surprises once you’ve found the right home.
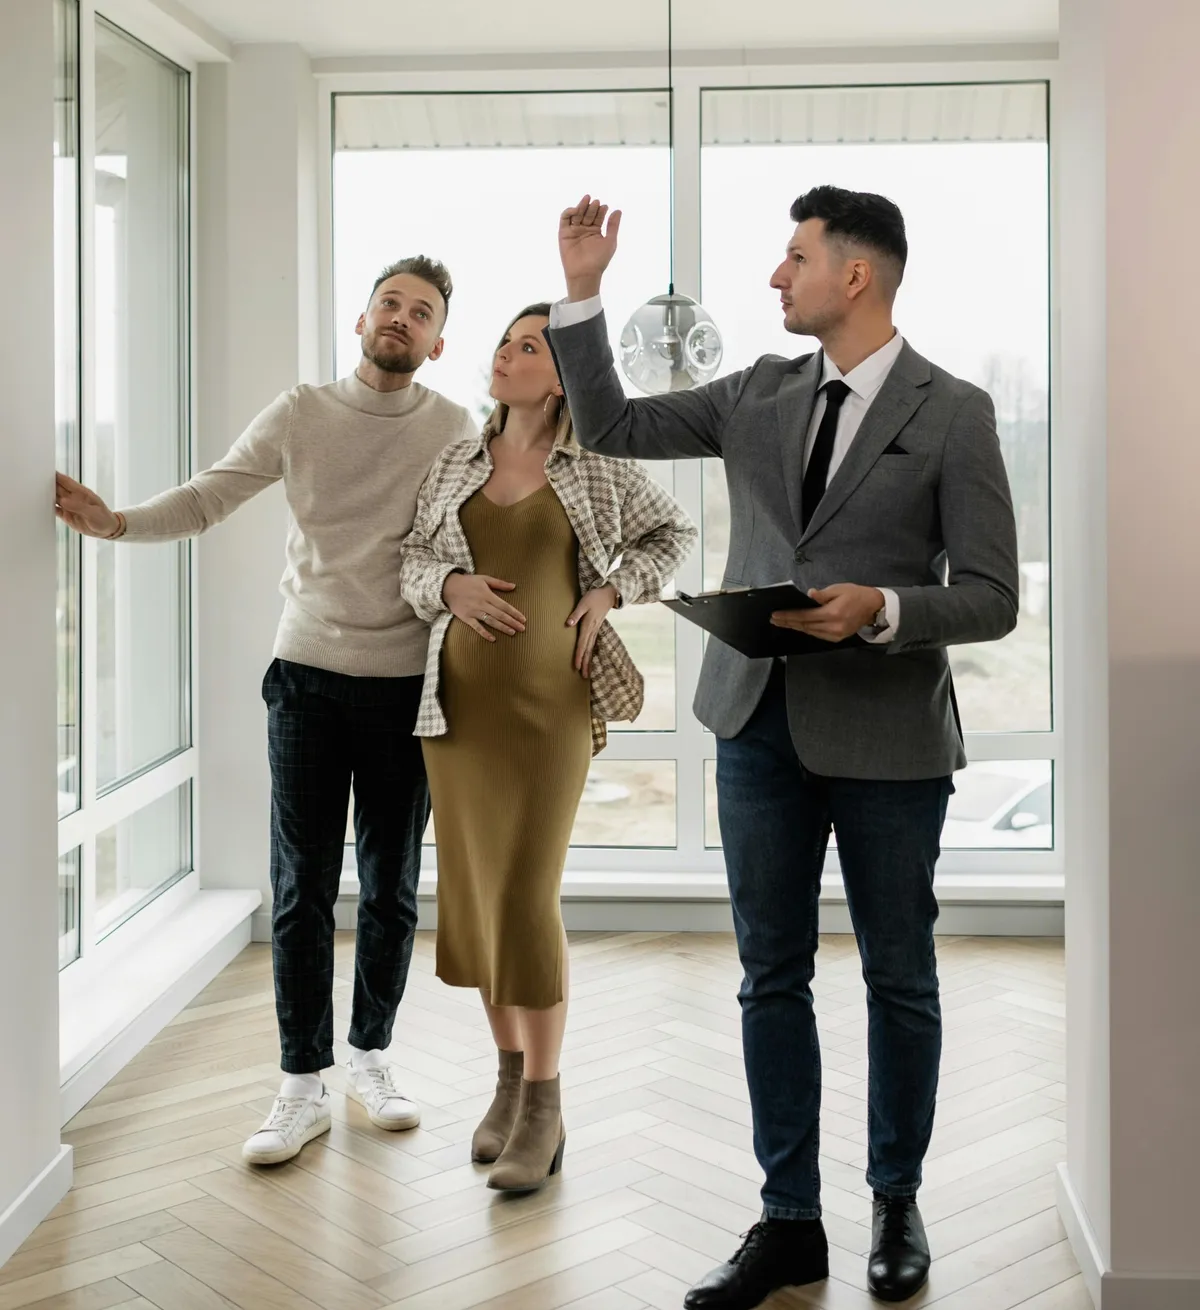
Is This the Right Time to Buy Your First Home?
This Service Is Ideal If You:
Are renting and want to build equity
Have stable income but limited savings
Are unsure how much home you can afford
Want to understand your mortgage options clearly
Need help navigating first-time buyer incentives
How much do I need for a down payment?
First-time buyers can purchase a home with as little as 5% down, depending on the purchase price and lender requirements.
What is a mortgage pre-approval?
A pre-approval confirms how much you can borrow, estimates your monthly payments, and strengthens your offer when buying a home.
Are there special programs for first-time buyers?
Yes. Many first-time buyers qualify for land transfer tax rebates, shared equity programs, and other government incentives.
What credit score do I need?
Credit requirements vary, but many lenders accept scores starting around 600–680, depending on income, down payment, and overall profile.
What costs should I plan for beyond the down payment?
Closing costs may include legal fees, land transfer tax, home inspection, appraisal, and title insurance—typically 1.5–4% of the purchase price.
Is it better to buy now or wait?
The right time to buy depends on your financial readiness and long-term goals. A personalized assessment can help you decide with confidence.
Guidance You Can Trust
First-time buyers benefit most from clear advice, honest numbers, and a strategy that protects them long after closing day. We focus on affordability, flexibility, and long-term success—not just getting you approved.
Your Path to Financial Freedom Starts Here
FSRA License #13564
BC License #MB605782
Stay Updated
Receive the latest mortgage insights and tips directly to your inbox.


